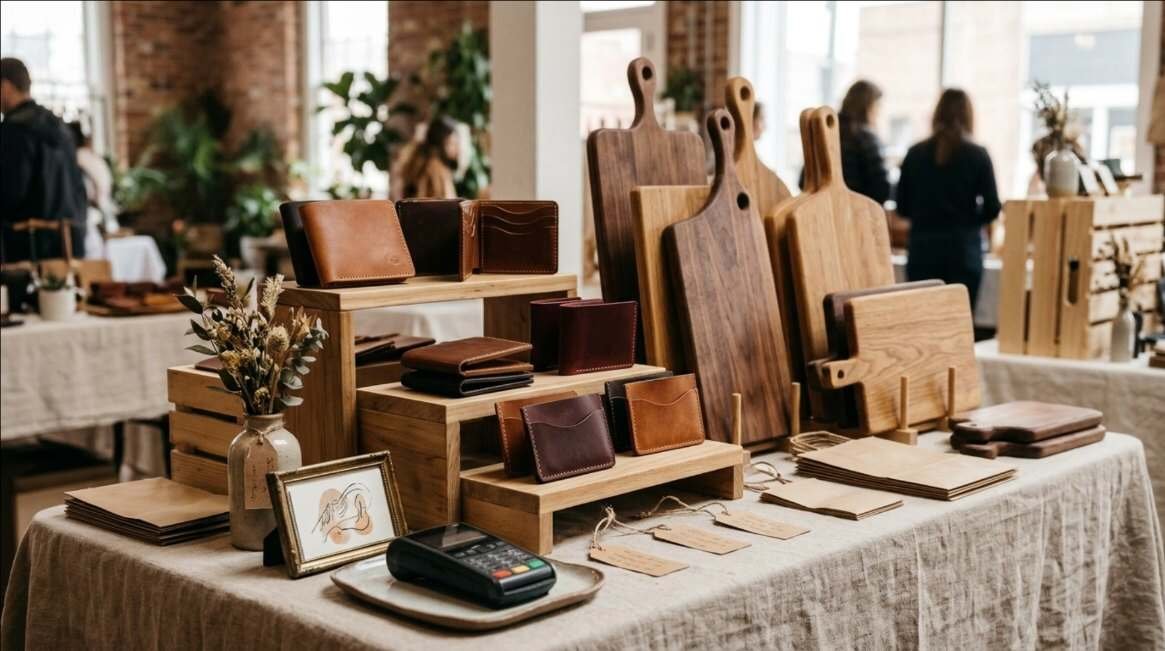
A table at a craft fair looks like the smallest possible business: a folding table, a cash box, a handful of finished pieces. To the New York State Tax Department, it is a retail sale of tangible personal property, and the rules attach to the first sale rather than the fiftieth. The Department’s own bulletin on registration says that sellers at craft fairs who sell taxable items must register, even if they sell only once a year, and a related bulletin states that taxable sales cannot legally begin until the Certificate of Authority has arrived.
This post covers New York sales only. A fair across the state line falls under that state’s rules, which differ. Everything below comes from Tax Department publications and the sales tax regulation, and it describes the general rule; a seller with an unusual product, such as food, services or a mix of both, should check the specific bulletin for that product.
Who has to register before a first booth
The baseline is stated plainly in the Department’s registration bulletin, TB-ST-175: “Sales of tangible personal property are subject to New York sales tax unless they are specifically exempt.” The same bulletin lists artwork and crafts among its examples of tangible personal property. Candles, ceramics, jewelry, woodwork and leather goods all fall into that group.
The regulation is more specific about shows. A person with no permanent place of business in New York who intends to sell taxable goods at a flea market, craft show, antique or coin show, fair or similar event must register under 20 NYCRR 533.1. A later set of amendments adopted in 2008 spells out what a show vendor does after registering: display the certificate prominently, and attach it to a cart, stand, truck or similar device when there is no fixed place of business.
Frequency does not change the answer. The registration bulletin from September 2011 puts it this way: “you must apply for a regular Certificate of Authority, even if your sales are only on an isolated or occasional basis.”
One weekend a year still counts
A maker who sells at a single holiday market each December is in the same position as one who works a fair every Saturday. The first has fewer returns to prepare over time, but both need the certificate before the first taxable sale.
The 20-day rule and the certificate itself
Registration runs through the Tax Department, and the timing is the part that catches people. The Department’s bulletin says registration must be made at least 20 days before beginning business. A maker who signs up for a fair three weeks out has almost no slack, and one who signs up the week before is already late. The 2011 bulletin describes a maximum penalty for operating without a valid certificate of $10,000, built from up to $500 for the first day and up to $200 for each day after. The regulation describes the same structure, with a $10,000 cap and possible criminal penalties.
Why the temporary certificate is off the table
New York offers a temporary Certificate of Authority for businesses expecting taxable sales over no more than two consecutive sales tax quarters in a twelve-month period. Show vendors are excluded. The bulletin says “Show and entertainment vendors may not apply for a temporary Certificate of Authority”, and Publication 750 repeats the point, adding that the Department no longer issues a separate certificate for show and entertainment vendors. A 2008 memo explains what replaced it: the Department stopped issuing Form DTF-726 and moved these vendors to Form DTF-17-A, which carries no expiration date.
Two consequences follow. A regular certificate does not lapse at the end of a season, so a vendor who stops selling needs a plan for closing it out (covered near the end of this post). And a certificate is tied to the business, not the booth: the bulletin notes that each business location needs its own certificate and that certificates cannot be transferred.
Which items carry tax, and which rate applies
Goods are taxable unless an exemption applies, and services are the reverse. Per the registration bulletin, services are generally exempt unless specifically taxable, with restaurant food and drink among the taxable ones. A maker who sells a finished leather wallet sells goods. A maker who sells a custom engraving on a customer’s own item is in territory that calls for a closer look at the bulletin on that service.
The rate follows the point of delivery
Publication 750 states that “the point of delivery generally determines the sales tax rate that applies to a transaction.” At a booth, the buyer takes the item on the spot, so the rate is the one for the location where the fair is held. Publication 718, effective March 1, 2025, lists Suffolk County at 8¾%, which includes the 3/8% imposed for the Metropolitan Commuter Transportation District. That was the edition available at the time of writing, and the Department’s rate page says the same publication applies, so the current edition should be checked before each season. A fair in a neighboring county or in New York City can carry a different combined rate.
On a $100 candle sold in Suffolk, the arithmetic at 8¾% is $8.75 in tax, as listed on the page fetched. Rates are printed per jurisdiction, so the table in Publication 718 is the reference, not memory or a sales tax calculator of unknown vintage.
Clothing under $110 splits the state and local tax
New York exempts eligible clothing and footwear costing less than $110 per item or pair from the 4% state tax. The Department states that local tax is exempt only in localities that enacted the exemption. Publication 718-C sorts jurisdictions into two groups, and it places Suffolk County among those that do not provide the local exemption, at a rate of 4¾%. In Suffolk, a $100 knit hat that qualifies as eligible clothing therefore carries the local 4¾%, or $4.75, but not the state 4%. Nassau County appears in the same second group at 4⅝%, while New York City appears in the group where such clothing is fully exempt. Whether a particular handmade garment counts as eligible clothing is a classification question for the Department’s clothing bulletin and not something this post settles.
What a show promoter checks, and why it matters to a vendor
A fair does not have to be run by one person, but the promoter carries obligations of its own. Form DTF-723, the show permit application, defines a promoter broadly: it includes anyone who operates four or more shows in a calendar year, rents or licenses space to vendors, or manages vendors making sales. According to the form’s instructions, the promoter must confirm that each vendor selling taxable goods holds a valid Certificate of Authority. The form lists penalties that include fines of up to $10,000 per show for allowing unregistered vendors to sell taxable items.
For a vendor, the practical result is that a missing certificate can cost a booth. The 2008 rule text says a promoter must not let anyone sell taxable items at a show unless that person has a certificate of authority and displays it. A promoter that rents tables or chairs to vendors also has its own registration duty, since those rentals are taxable (per TB-ST-175).
Pop-ups, home sales and the casual sale exception
A pop-up sale in a shop’s back room, a farmers market stall or a parking lot is, for tax purposes, a sale by a vendor, and the same registration rule applies. The one real carve-out is the casual sale. TB-ST-175 defines it as an occasional or isolated taxable sale by someone not in the business of selling taxable goods or services, and says that people making casual sales from home, with no intent to sell regularly and with buyers picking up at the home, generally do not need to register. Tax can still be due on those sales, and garage sale rules do not apply when the selling price exceeds $600; the bulletin points to Form ST-131 for reporting.
That carve-out is narrow. A maker who produces goods to sell, takes a table at a fair, and returns the following month is in the business of selling, whatever the scale. The same bulletin lists home-based businesses that make taxable sales among those that must register. The choice of venue between fairs and online, which affects how often registration is needed in the first place, is covered in Craft Fairs or Online: Where a Maker Should Sell First, and the broader process of setting up a business in New York is laid out in Registering a Business in New York: Assumed Name and Sales Tax.
Collecting, recording and filing
Collecting the tax is the vendor’s job. The bulletin on registration says that generally, the seller collects the tax from the purchaser and remits it to New York State. At a fair, that means a cash box and a card reader that both account for tax separately from the price of the goods. A seller taking cards at the booth can compare processors in Taking Card Payments With Square: Setup and Fees.
Records for cash sales
The Department’s recordkeeping bulletin says to keep a true copy of each sales slip, invoice or receipt. Where no written document goes to the buyer, as at many tables, the bulletin calls for a detailed daily record of cash and credit sales in a daybook or similar journal. Records must be kept for a minimum of three years from the due date of the return, or from the filing date if that is later, and the Department can require longer, for instance during an audit. The general question of which business records to hold and for how long is covered in What Records a Small Business Keeps and for How Long.
Returns, including the months with no sales
Most new vendors start as quarterly filers on Form ST-100. The filing bulletin lists the periods as March 1 to May 31, June 1 to August 31, September 1 to November 30, and December 1 to the end of February, with returns generally due no later than 20 days after the end of the period. A vendor who owes $3,000 or less in tax for the annual period can be an annual filer on Form ST-101, and annual returns are due by March 20.
The detail that matters for seasonal sellers: once registered, a return is due even when nothing sold. The bulletin says that the minimum penalty for late filing is $50, even if no tax is due. A vendor whose only fair falls in December still has returns for the quarters before and after it. The Department’s filing page adds that no-tax-due returns and final returns can be filed through Web File.
Ending the season, or the business
Because a show vendor’s regular certificate has no expiration date, it stays active until someone ends it. The regulation says a show vendor must surrender the certificate, with a final return, within 20 days after ceasing to participate in shows in New York. A maker who plans to sell again next year can keep the certificate and file the returns in between. One who has stopped for good closes it out. Neither choice is automatic, and the deadline in the second case runs from the date selling stops.
Two cautions apply to every case above. The Department’s bulletins carry different issue dates, from 2011 to 2021 with later web updates, and rates and thresholds can change between editions. And a seller with questions about a specific product, a mixed sale of goods and services, or sales in more than one state belongs in a conversation with a tax professional or the Tax Department.
For informational purposes only — consult a licensed attorney, tax professional or financial advisor.
Sources
- https://tax.ny.gov/pubs_and_bulls/tg_bulletins/st/do_i_need_to_register_for_sales_tax.htm
- https://www.tax.ny.gov/pdf/tg_bulletins/sales/b18_360s.pdf
- https://www.law.cornell.edu/regulations/new-york/20-NYCRR-533.1
- https://tax.ny.gov/pdf/rulemaking/nov0408/sut_vendors/text.pdf
- https://www.tax.ny.gov/pdf/memos/sales/m08_13s.pdf
- https://www.tax.ny.gov/pdf/publications/sales/pub750.pdf
- https://www.tax.ny.gov/pdf/publications/sales/pub718.pdf
- https://nystax.gov/pdf/publications/sales/pub718c.pdf
- https://www.tax.ny.gov/bus/st/sales_tax_clothing_exemption.htm
- https://www.tax.ny.gov/pdf/current_forms/st/dtf723i.pdf
- https://tax.ny.gov/pubs_and_bulls/tg_bulletins/st/record-keeping_requirements_for_sales_tax_vendors.htm
- https://www.tax.ny.gov/pubs_and_bulls/tg_bulletins/st/filing_requirements_for_sales_and_use_tax_returns.htm
- https://tax.ny.gov/bus/st/filing_sales_tax_returns.htm
- https://www.youtube.com/watch?v=Ls-eLtRA4F4
All pages fetched November 8, 2026.