A chicken plate at $20 for a party of 100 becomes an $18 plate when the party grows to 150, in a worked example from the invoicing company FreshBooks. The restaurant that signs that second quote is betting its costs per plate fall faster than its price. A tray that sells well over the counter can lose money once labor, transport, disposables, rentals and the length of an event are counted against it, and the published guides that try to settle the math agree on the shape of the problem while disagreeing, sometimes sharply, on every target number.
Every catering quote is built fresh, around a guest count that can still move after the deposit clears.
Costs that sit on top of the food
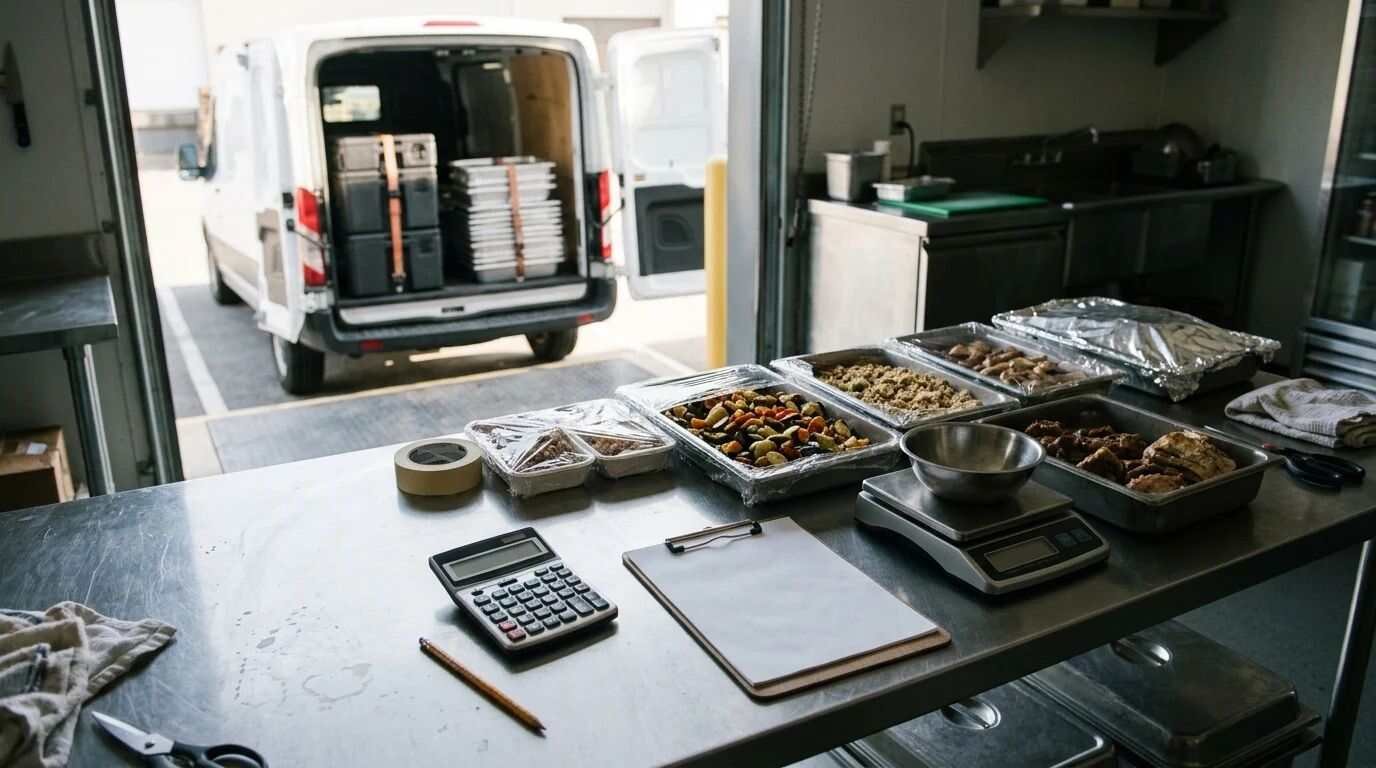
Nicolet College’s open textbook Catering, written by Vicki Mendham and published in 2025, treats cost accounting as the first step of pricing. Its list of items to account for is long: labor, food, disposables and packaging, delivery and transportation, time, overhead such as insurance, license fees, utilities and maintenance, cleanup, dishes, rentals, venue charges, equipment, decorations, gratuities, taxes and service charges. The list also separates drop-off orders from events where staff stay on site, since the second kind adds hours of labor that the first does not.
The FreshBooks guide orders the same material as a quote, built in sequence: guest count, food, supplies and rentals, bar, service charge, and finally taxes and the total. The guide advises writing a policy for guest-count changes and guarantees into the estimate itself.
One gap shows up across the sources. A Galley Solutions blog post on catering profitability covers food cost, labor, overhead and markup, and its summary of topics leaves out delivery fees, event minimums and packaging. A tray of food that travels in a van, in disposable pans, with a driver on the clock, carries costs that never appear on a recipe card. A recipe costing card covers the ingredient side; the rest has to be added by hand.
Per person, per tray and other pricing models
Mendham lists four common ways to express a catering price. Per person is the most common. Per tray or per dish suits drop-off orders. A flat rate fits small events. Hourly pay plus the cost of food fits private-chef or custom work. Drinks are priced separately, per drink, per bottle or as a per-guest package covering a block of time, and the textbook advises rounding drink prices up and including tax.
The same chapter recommends tiers, with Basic, Standard and Premium versions of a menu. A tiered menu gives a buyer a way to move up or down without asking the restaurant to rebuild the quote.
FreshBooks draws a different line, between fixed and tiered prices. Under fixed pricing, the chicken plate costs $20 whatever the headcount. Under tiered pricing it drops to $18 at 150 guests, which rewards size and also commits the restaurant to a lower price on large orders, a promise that only holds if costs fall with volume.
Portion assumptions sit behind any per-person price. The FreshBooks guide estimates a plated meal at about four to six ounces of meat, two sides, an appetizer and dessert for each guest, and notes that children eat about half as much as adults. The guide notes that buffet and plated meals differ in how much food each guest needs.
Food cost targets and the formulas behind them

Food cost percentage is the share of the selling price taken by ingredients. Galley’s definition is the ingredient cost divided by the selling price, and its example is $3 of ingredients on a $10 item, or 30 percent. The restaurant-side math is covered in a separate post on how to calculate food cost percentage. Catering sources do not agree on one target number.
Three sources give three ranges. Mendham’s textbook gives a food cost target of 18 to 25 percent. Galley gives 28 to 35 percent as typical, with high-end caterers running near 25 percent and volume caterers near 40 percent. FreshBooks reports that food runs about 30 percent of the total price, citing a Houston Chronicle account, and suggests 24 to 28 percent for better profits. A restaurant that lands inside one range can sit outside another, so the honest use of any of them is as a figure to test against the restaurant’s own books.
Two formulas turn a cost into a price. The first, from Mendham, divides the cost per person by the approved food cost percentage. The second comes from Galley and works from a target gross margin: price equals total cost divided by one minus the margin. Galley’s worked example takes a cost of $11 and a 68 percent margin and arrives at $34.38, rounded to $34.99. The same post shows the simpler cost-plus method, where $11 with a 30 percent markup becomes $14.30, rounded to $14.99. The two methods give very different answers from the same cost, and the gap comes from what each percentage is measured against: markup is a share of cost, and margin is a share of price.
Profit targets are as scattered as food cost targets. Galley puts the target gross margin for catering at 65 to 70 percent. Mendham gives desired profit as 12 to 30 percent or more, and a typical catering profit margin as 15 to 30 percent, with premium services sometimes higher. FreshBooks describes a good profit margin as about 7 to 8 percent and cites a standard markup of about three times food cost. Those figures describe different yardsticks, gross in some pages and net in others, so a restaurant comparing itself to them has to match the definition before it matches the number. The profit and loss statement shows where each of those measures sits in a restaurant’s own records.
Labor, overhead, rentals and the bar
Galley puts labor at roughly 25 to 35 percent of total catering revenue, counting prep, administration and some owner time. Its example takes $5,000 of revenue, from 100 guests at $50 each, and a 30 percent labor share, which leaves $1,500 for staffing. The post on labor cost and scheduling covers the habit of measuring labor against sales that catering quotes need.
Overhead gets spread across events instead of days. Galley’s example divides $10,000 of monthly overhead across 20 events for about $500 an event, and FreshBooks uses $5,000 across ten jobs for the same $500. Both examples make the same point: a small event carries the same fixed cost as a large one, and a low guest count can sink an order that looks fine per plate.
That cuts against the tiered discount from earlier, though not in the direction it first appears. Overhead is the one line here that plainly shrinks per guest as the count grows, since $500 spread over 150 plates is less than $500 over 100. Food does not shrink that way; the FreshBooks portion guide still puts four to six ounces of meat in front of every adult. A discount for size is really a bet that overhead and a few efficiencies outrun the food, and on a small event the bet can be lost before the van is loaded.
Rentals add a per-person charge when a customer needs tables, linens or chafing dishes that a restaurant does not own. FreshBooks cites $2 to $6 per person for rentals, $2 to $4 per person for bar service, and a service charge of $5.50 to $9 per person, all from its own examples, which carry no date. The guide also reports alcohol costing two to three times as much as food in some events, and observes that bars at events can get expensive. Galley treats the bar as a profit center, with markups of 200 to 300 percent over cost described as common, and tells readers to check local alcohol regulations.
Guest counts and contract terms

A catering price is only as firm as the guest count behind it. Mendham advises that the contract state the number of guests the caterer will prepare for. Her textbook describes an “over” method for events that grow: the caterer charges for the extra guests plus 30 to 50 percent, which discourages underestimating. Charges usually are not reduced when fewer guests attend.
Timing carries a price too. The textbook recommends stating late-meal times and fees in the contract, because staff costs rise as an event runs long and food held past its service time loses quality. The same chapter recommends that a proposal spell out all prices, so that the customer meets no surprise charge later.
Pricing also needs maintenance. Mendham advises comparing competitors’ per-person rates, service fees, minimum orders and add-on prices within the same niche, tracking profit on each event, collecting client feedback, and reviewing prices every six to twelve months, or sooner when food prices are volatile. A FreshBooks passage adds a warning against cutting prices to match competitors, which can hurt cash flow and long-term survival.
Sales tax on catering in New York
New York’s Department of Taxation and Finance addresses catering in Tax Bulletin ST-110, Caterers and Catering Services, issued April 8, 2019. The bulletin says a caterer’s charges for food, beverages and any services provided for a customer’s event are subject to sales tax. It says a service charge is always subject to sales tax. Voluntary tips are not taxable. A mandatory gratuity is nontaxable only when it appears separately on the bill, is labeled as a gratuity, and all of the money collected goes to employees.
The bulletin also covers what a caterer pays tax on. Tables, chairs, tents, linens and kitchen equipment bought by a caterer carry sales tax from the supplier, and the caterer cannot claim a credit for that tax. Wait staff, bartenders, bands and similar workers hired for an event are nontaxable purchases for the caterer, but the caterer still charges the customer sales tax on those amounts when billing for them. A caterer that only delivers food, with no other services after delivery, is making an off-premises sale, which the bulletin refers to a separate bulletin, TB-ST-806, to describe. Sellers of taxable items for resale need a properly completed Form ST-120 resale certificate from the buyer.
Tax bulletins can be revised after issue, and a related post covers collecting and filing sales tax in New York for online sellers. One line at the bottom of the invoice carries more weight than it looks. Under the bulletin, a mandatory gratuity that is labeled as one, listed separately and paid in full to the staff is not taxable, while a service charge always is, so two charges of the same size on the same party can carry different tax depending on a word and where the money goes.
For informational purposes only — consult a licensed attorney or financial advisor.
Sources
- Catering, “7 Pricing Catering Menus,” Vicki Mendham, Nicolet College (2025)
- How To Price A Catering Menu for Profitability, Ian Christopher, Galley Solutions
- How to Charge for Catering: A Complete Pricing Guide, FreshBooks
- Caterers and Catering Services, Tax Bulletin ST-110, NYS Department of Taxation and Finance
- How to Price Catering Menus for Profit | Beginner Caterers Guide, Morin Hospitality (YouTube)